Moving home is exciting, but let’s be honest, the costs can make your wallet weep. One of the biggest expenses you’ll face as a buyer is Stamp Duty Land Tax (SDLT). Don’t worry, though, we’re here to break it all down, so you know exactly what you’re dealing with.
Think of this as your friendly guide through the stamp duty maze. We’ll cover everything from how much you’ll pay, to clever ways you might save a few quid. No jargon, no confusing legal speak, just the facts you need to budget appropriately for your home purchase.
What is Stamp Duty Land Tax (SDLT)?
Stamp duty is a tax you pay to the government when you buy a property in England or Northern Ireland. It’s calculated as a percentage of your property’s purchase price, and yes, it can add up to quite a chunk of change.
The good news? Not everyone pays the same rate, and some handy exemptions might help reduce your bill. The amount you pay depends on several factors, including the property price, whether you’re a first-time buyer, and whether you already own another property.
Stamp Duty is one of several significant costs to budget for when buying a property. For a full breakdown of every fee involved, see our guide to the hidden costs of buying a house.
2026 Stamp Duty rates and thresholds
Standard residential property rates
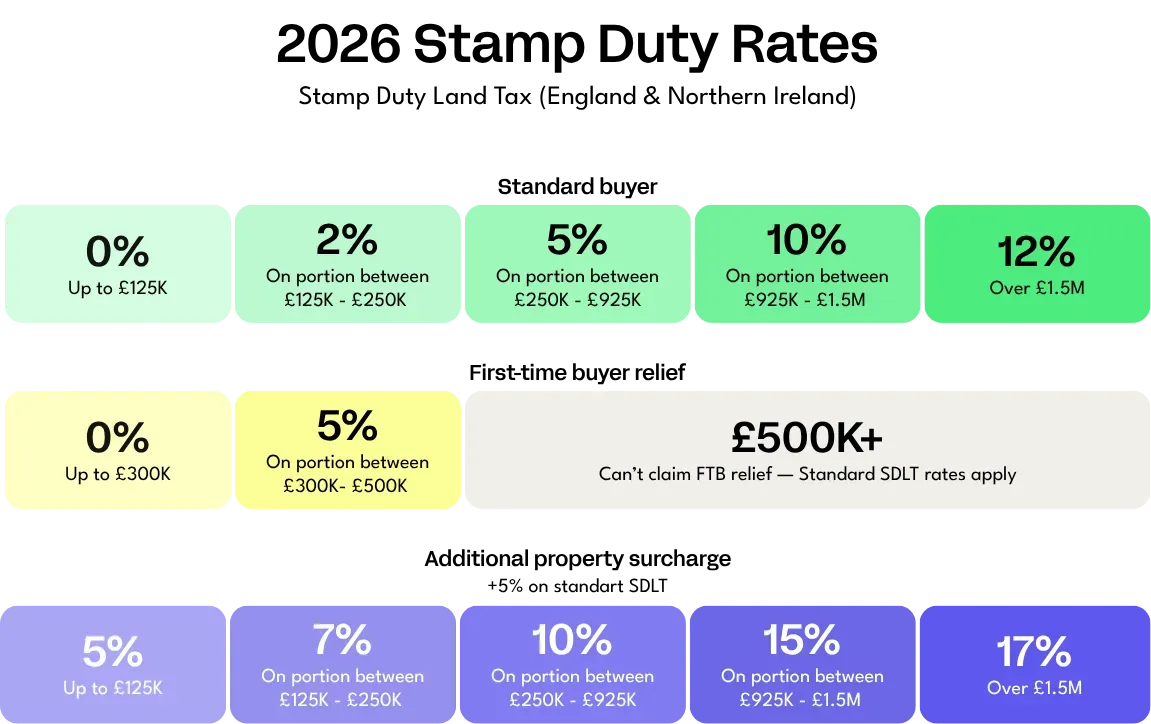
Here’s how the current Stamp Duty bands work for most home buyers:
| Property prices
|
SDLT
| | — | — | |
up to £125,000
|
0% (that’s right, nothing to pay!)
| |
£125,001 to £250,000
|
2%
| |
£250,001 to £925,000
|
5%
| |
£925,001 to £1.5 million
|
10%
| |
over £1.5 million
|
12%
|
The clever bit is that you only pay the higher rate on the portion of the price that falls into each band, not the entire purchase price.
First-time buyer relief
First-time buyers get a helping hand with reduced rates:
- £0 to £300,000: 0% (even better than the standard rate!)
- £300,001 to £500,000: 5%
This relief applies to properties up to £500,000. If the property price is over £500,000 you can’t claim the relief, and you will need to follow the rules for standard buyers. When buying a property over £500,000, then you’ll pay the standard rates on the amount above the £500,000.
New to buying? Our first-time buyer guide covers deposits, mortgages and everything else you need to know.
Additional property surcharge
Already own a property? You’ll face an additional 5% surcharge on top of the standard rates for any additional properties. This applies to second homes, buy-to-let investments, and holiday homes.
How to calculate your Stamp Duty bill
Let’s work through a real example to make this crystal clear.
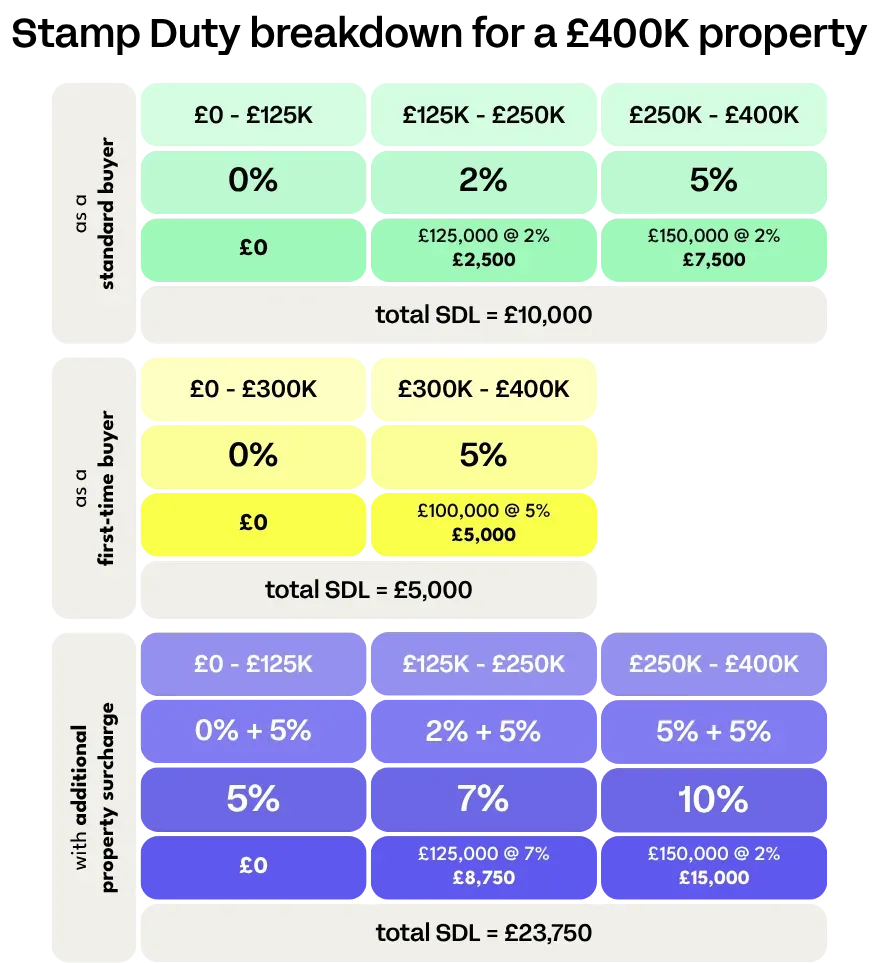
If you’re buying a property worth £400,000, you’ll pay:
- £10,000 on Stamp Duty Land Tax as a standard buyer.
- as a first-time buyer that bill goes down to £5,000. Pretty significant difference, right? This is why understanding your eligibility for reliefs is so important.
- £23,750 as a second home or additional property.
You can also use the official HMRC stamp duty calculator to get an exact figure for your purchase price.
Who qualifies as a first-time buyer (FTB)?
To qualify for first-time buyer relief, you must:
- Have never owned a property anywhere in the world.
- Be buying a property worth £500,000 or less.
- Intend to live in the property as your main residence.
If you’re buying with a partner, both of you must be first-time buyers to qualify for the relief. If one of you has owned property before, you’ll pay the standard rates for Stamp Duty. You can check the full first-time buyer relief criteria on GOV.UK.
Stamp Duty exemptions and reliefs
Properties under £125,000: Any residential property costing £125,000 or less is completely exempt from stamp duty. This makes smaller properties and many regional homes particularly attractive for budget-conscious buyers.
Shared ownership schemes: If you’re buying through a shared ownership scheme, you only pay stamp duty on the portion you’re purchasing, not the full market value. You can also elect to pay stamp duty on the full market value upfront to avoid paying more later when you “staircase” (buy additional shares).
Transfers between spouses: Transferring property between married couples or civil partners is generally exempt from stamp duty, if it’s done as part of a formal, written divorce or separation agreement signed by both, or following a court order because you’re divorcing or dissolving a civil partnership — provided there are no other buyers involved.
When and how to pay Stamp Duty
You’ve got 14 days from the completion date to file your Stamp Duty return and pay the tax. Miss this deadline, and you’ll face penalties and interest charges — not exactly the housewarming gift you want.
Your solicitor or conveyancer will typically handle this for you as part of the purchase process. They’ll calculate the amount due, complete the necessary paperwork, and ensure payment reaches HMRC on time. For full details on filing and payment, see the HMRC guidance on Stamp Duty Land Tax.
Not sure what your conveyancer does? Read our guide on how long conveyancing takes and what’s involved.
Regional differences in Stamp Duty
Scotland: Land and buildings transaction tax (LBTT)
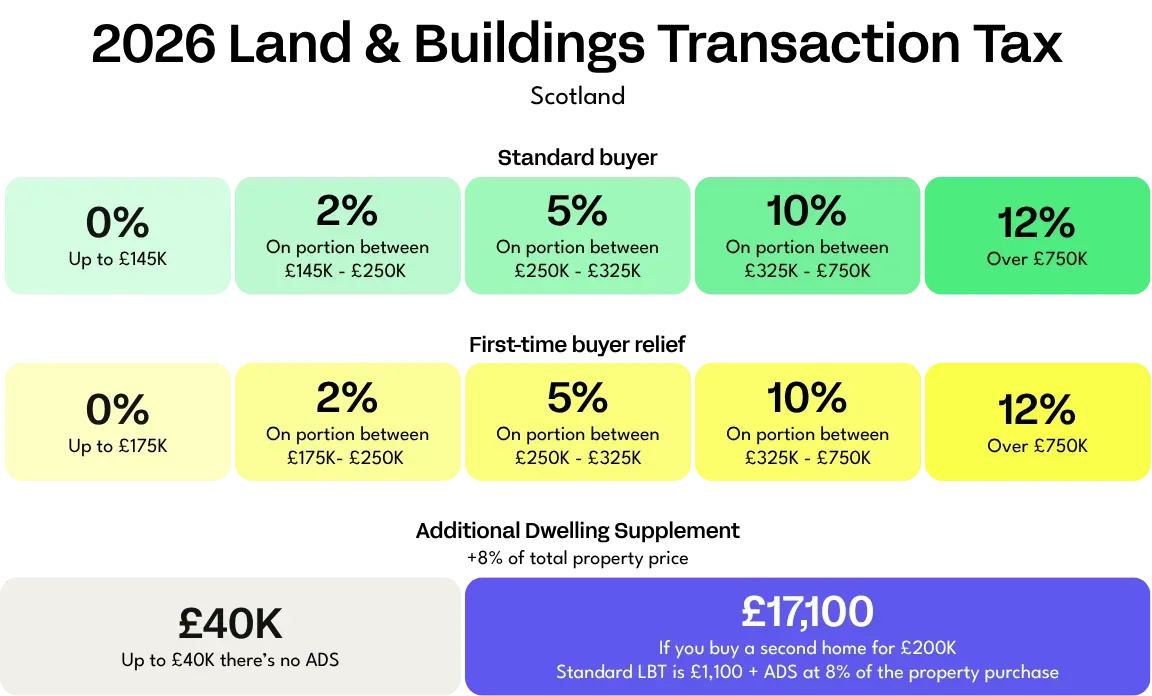
Scotland has its own property tax system called Land and Buildings Transaction Tax, with different rates and thresholds to England and Northern Ireland:
| Property price
|
LBTT
|
| | — | — | — | |
£0 to £145,000
|
0%
| | |
£145,001 to £250,000
|
2%
| | |
£250,001 to £325,000
|
5%
| | |
£325,001 to £750,000
|
10%
| | |
over £750,000
|
12%
| |
First-time buyers in Scotland don’t pay LBTT on properties up to £175,000. The remainder is exactly the same as a standard purchase.
Buyers purchasing a second or additional property pay an Additional Dwelling Supplement (ADS), applied at 8% of the total purchase price — this is paid in addition to any LBTT. Properties under £40,000 are not subject to ADS.
Wales: Land Transaction Tax
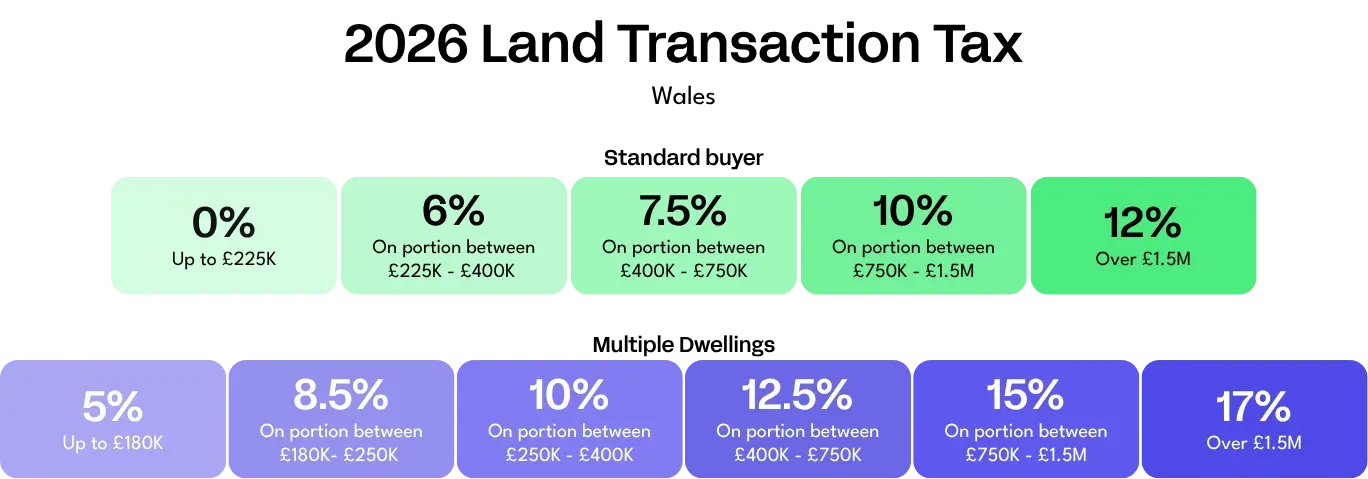
Wales operates its own system called Land Transaction Tax, administered by the Welsh Revenue Authority. There’s no first-time buyer relief available in Wales.:
| Property price
|
Standard LTT
|
Property price
|
Multiple Dwellings LTT
| | — | — | — | — | |
£0 to £225,000
|
0%
|
£0 to £180,000
|
5%
| |
£225,001 to £400,000
|
6%
|
£180,001 to £250,000
|
8.5%
| |
£400,001 to £750,000
|
7.5%
|
£250,001 to £400,000
|
10%
| |
£750,001 to £1.5 million
|
10%
|
£400,001 to £750,000
|
12.5%
| |
over £1.5 million
|
12%
|
£750,001 to £1.5 million
|
15%
| | | |
over £1.5 million
|
17%
|
Smart ways to reduce your Stamp Duty bill
**Time your purchase strategically
**Keep an eye on government announcements. Temporary reliefs and threshold changes do happen and timing your purchase around these can save thousands.
**Consider property price negotiations
**If you’re close to a stamp duty threshold, negotiating the price down even slightly can sometimes drop you into a lower band, saving more than the reduction in purchase price.
**Separate land and property purchases
**In some cases, particularly for new builds, you might be able to purchase the land and property separately to optimise your stamp duty position. This is complex territory though, worth discussing with your solicitor.
**Chattels and fixtures
**If the seller has left items such as carpets, curtains, ovens or furniture behind, make sure the cost of these fixtures and fittings haven’t been factored into the property price. This only makes your stamp duty bill higher. Offer to pay for these items separately so they’re not taxable. Again, professional advice is essential here as HMRC might think you’re taking things too far.
Common Stamp Duty mistakes to avoid
Missing the 14-day deadline: This is the big one. Late filing means penalties starting at £100, plus daily charges and interest. Your solicitor should handle this, but it’s worth keeping an eye on the timeline.
Incorrectly claiming first-time buyer relief: HMRC takes a dim view of false claims. Make sure you genuinely qualify before claiming any reliefs, the penalties for getting it wrong are severe.
Forgetting about additional properties: If you own any property anywhere in the world, you’ll likely face the additional property surcharge. This includes inherited properties you might have forgotten about.
Not considering future plans: Buying a property you plan to rent out immediately? You’ll pay the additional property surcharge even if it’s your first purchase. Think about your intentions carefully.
If you’re buying in a chain, read our guide to buying a house in a chain to understand how completion timelines work.
Stamp Duty and new build properties
New build properties follow the same stamp duty rules, but there are a few extra considerations:
- Help to Buy schemes: These can affect your stamp duty calculation.
- Shared ownership: You might pay stamp duty differently depending on your purchase structure.
- Off-plan purchases: The stamp duty is based on the final purchase price, not any deposit paid during construction.
Planning your moving budget
Stamp duty should be a key part of your moving budget calculations. Here’s what else to factor in:
- Legal fees: Typically £1,000-£2,000 — get multiple quotes to compare costs.
- Survey costs: £300-£1,500 depending on the type of survey — find out the cost.
- Removal costs: Compare firms and costs to find the best deal.
- Home insurance: Required to exchange contracts.
- Emergency fund: Always good to have a buffer for unexpected costs.
Remember, Stamp Duty is paid on completion, so you’ll need this money available alongside your deposit and other moving costs.
For a full breakdown, see our guide to the hidden costs of buying a house.
Making Stamp Duty work for your move
Understanding Stamp Duty doesn’t have to be a headache. Armed with the right information, you can budget accurately and maybe even find ways to reduce your bill legally. The key is getting professional advice tailored to your specific situation. Every property purchase is different, and what works for your mate down the pub might not work for you.
Remember, while Stamp Duty is a significant cost, it shouldn’t be the only factor in your property decision. Focus on finding the right home for your needs and budget, then factor in all the associated costs, including stamp duty, to make sure everything adds up.
In a nutshell
Moving house is a big step, but with the right preparation and understanding of costs, you’ll be well-equipped to make confident decisions. After all, knowledge is power, and in this case, it might just save you some serious money too.
FAQs
Do I pay Stamp Duty if I'm buying with a mortgage?
Yes. Stamp Duty is based on the property's purchase price, regardless of how much you borrow. Cash buyers and mortgage buyers pay the same rate.
Can I claim Stamp Duty back if the sale falls through?
No. Stamp Duty is only paid upon completion. If your purchase collapses before completion, no SDLT is payable. If completion does occur but the transaction is later rescinded within 12 months, you may be able to apply to HMRC for a refund, but this is rare and subject to specific conditions.
What happens if I buy jointly with someone who isn't a first-time buyer?
If even one buyer has owned property before, the purchase does not qualify for first-time buyer relief. All buyers must be first-time buyers to claim the relief.
Do I pay Stamp Duty on shared ownership properties?
You pay SDLT on the portion you are buying. You can choose to pay on the full market value upfront to avoid additional tax later when staircasing.
Is Stamp Duty the same across the whole UK?
No. England and Northern Ireland use SDLT, Scotland uses LBTT, and Wales uses LTT. Rates, thresholds, and surcharge rules differ between these systems.
Can I reduce Stamp Duty by buying furniture separately?
Potentially. Fixtures and fittings sold separately do not count toward the SDLT calculation, but deductions must be reasonable and well documented to avoid HMRC challenge.
What if I'm buying a property to renovate and sell?
If you already own another property, you will likely pay the additional 5% surcharge at completion. However, if you sell your previous main residence within 36 months of completion, you can apply to HMRC for a refund of the surcharge, so keep records carefully.
Do overseas buyers pay more stamp duty?
Yes. Non-UK residents pay an additional 2% surcharge on top of all standard SDLT rates. You are considered a non-UK resident for this purpose if you have spent fewer than 183 days in the UK in the 12 months before your purchase.